
New York mandatory liability insurance minimum 25/50/25 coverage limits are the legal requirement every New York driver must meet to keep their registration and license valid. If you’ve seen those numbers on an insurance quote or DMV notice and wondered what they cover, you’re not alone. Most drivers assume the state minimum covers any accident they cause.
That assumption is a costly mistake.
Set by New York Vehicle and Traffic Law § 311, the limits break down to $25,000 per person for bodily injury, $50,000 total per accident for bodily injury, and $25,000 for property damage. As of 2026, the $25,000 per-person cap hasn’t increased since 1992, even as medical and repair costs rise. We’ll break down what those numbers mean, the real costs of underinsuring, and when the state minimum is actually enough for you.
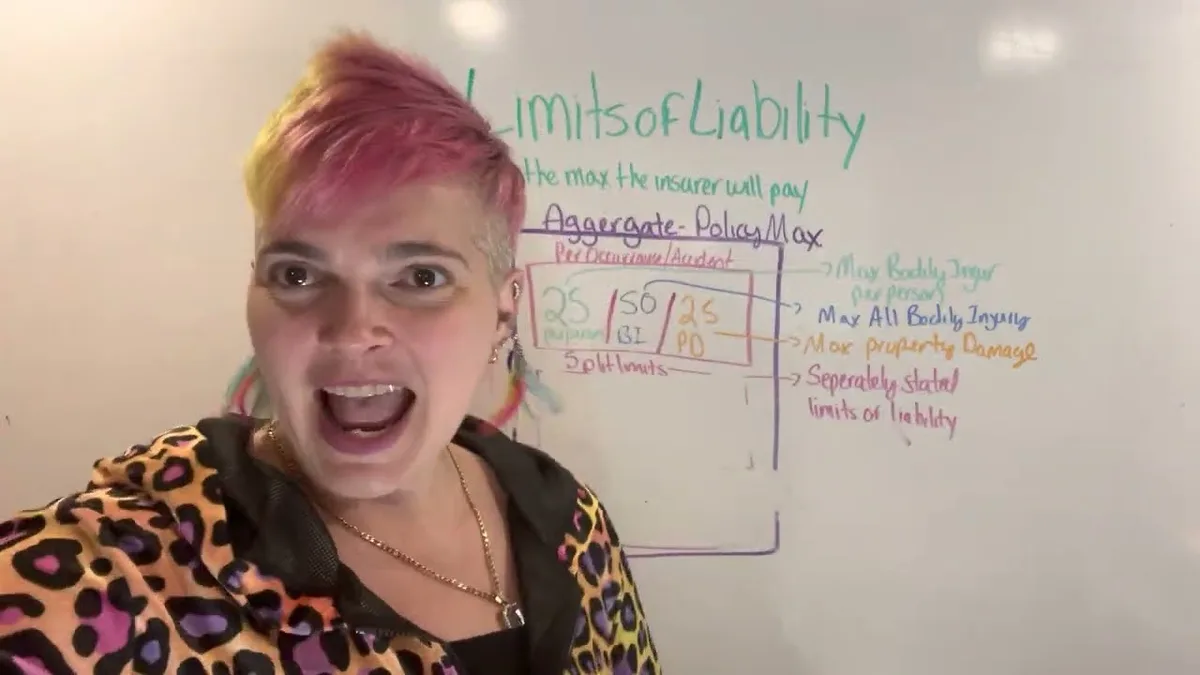
Why Getting New York’s 25/50/25 Minimum Insurance Rules Right Matters
New York’s 25/50/25 minimum liability limits are not a suggestion. They are a legal requirement tied directly to your ability to register a vehicle, maintain a valid driver’s license, and avoid severe financial penalties. The state’s automated insurance verification system checks your policy status against DMV records in real time.
There is no grace period for lapses or incorrect coverage. Even out-of-state drivers operating a vehicle in New York for as little as 30 days must meet these limits.
New York is a no-fault insurance state. Your own policy’s personal injury protection (PIP) coverage pays for your medical bills first after an accident, regardless of who is at fault. The 25/50/25 liability limits apply only to damages you cause to other people and their property.
Misunderstanding that distinction leads to huge coverage gaps when you need help most.
New York’s 25/50/25 Minimum Liability Limits: Exact, No Guesswork
Every part of the 25/50/25 figure maps to a specific liability coverage requirement with a fixed maximum payout your insurer will provide for a covered at-fault claim. These caps apply to damages you cause to other people and their property, not your own costs. New York also requires a separate minimum $50,000 in personal injury protection (PIP) coverage as part of every mandatory auto policy.
| Coverage Type | What It Covers | New York Minimum Required |
|---|---|---|
| Per-person bodily injury liability | Medical bills, lost wages, and pain and suffering for one person you injure in an at-fault accident | $25,000 |
| Per-accident bodily injury liability | Total payout for all bodily injury claims from a single accident you cause | $50,000 |
| Property damage liability | Repairs or replacement of another person’s vehicle, property, or infrastructure you damage in an at-fault accident | $25,000 |
| Personal injury protection (PIP) | Your own medical bills, lost wages, and essential services after an accident, regardless of fault | $50,000 |
These limits apply to all passenger vehicles registered in New York, including cars, light trucks, and vans under 10,000 lbs. If you operate a vehicle registered in another state in New York for more than 30 days, you must also carry coverage that meets or exceeds these limits. Per New York Department of Financial Services public records, these minimums have remained unchanged since 1992 as of 2026.
You can choose to purchase higher coverage limits when you shop for a policy for a small extra monthly premium.
The Real Costs of Getting This Wrong (It’s Way More Than a Ticket)
Driving without New York’s required minimum insurance leads to immediate, cascading penalties that go far beyond a simple traffic ticket. The state enforces these rules aggressively, with penalties that can derail your finances and your ability to drive for months or even years.
- First offense no-insurance fine: $150 to $300, plus court costs
- Daily late fee for lapsed coverage: $50 per day, assessed every day until you provide valid proof of insurance
- Automatic driver’s license suspension for at least 30 days for a first offense, with longer suspensions for repeat offenses
- Vehicle registration suspension, meaning you cannot legally drive the car until you pay all reinstatement fees and provide proof of coverage
- Court-ordered judgments if you cause an accident while uninsured or underinsured, which can lead to wage garnishment, property liens, or even bankruptcy in severe cases
Even if you carry the minimum required coverage, you can still face massive out-of-pocket costs if you cause a serious accident. The 2023 average cost of a New York bodily injury claim topped $22,000, per New York DFS data. If you cause an accident that leaves one person with $80,000 in medical bills, your $25,000 per-person liability limit covers just 31% of that cost.
You pay the remaining $55,000 out of pocket, plus any property damage over your $25,000 cap. A 2023 NAIC report found that 17% of New York drivers carry only the state minimum coverage, leaving them exposed to exactly this kind of financial risk.
Who Actually Needs More Than the 25/50/25 Minimum?
The 25/50/25 state minimum works for a very small subset of drivers, but most people are far better off with higher coverage limits. The threshold for needing extra coverage comes down to your assets, driving habits, and risk profile.
If you own a home, have savings, retirement accounts, or other significant assets, the state minimum is almost certainly too low. A serious at-fault accident can easily exceed the 25/50/25 caps, putting those assets at risk if you are sued for the remaining damages. Umbrella insurance policies, which provide $1 million or more in additional liability coverage for a small monthly premium, are a common option for high-net-worth drivers looking for extra protection.
If you drive for a ride-share service (Uber, Lyft) or deliver goods for a company, your personal policy’s minimum limits will not cover you while you are working. Most ride-share and delivery companies require drivers to carry at least 100/300/50 in liability coverage while on the job.
Teen and new drivers under 21 are three times more likely to be involved in a fatal crash than experienced drivers, per New York DMV data. This makes higher liability limits a smart investment for families with new drivers on their policy.
If you regularly drive in high-traffic, high-cost areas like New York City, Long Island, or Buffalo, accident costs are far higher than the state average. Property damage and medical bills in these areas often exceed the 25/50/25 caps even for minor fender-benders.
The only group for whom the state minimum may make sense is drivers with no significant assets, who drive an old, low-value vehicle, and who can comfortably cover any out-of-pocket costs if they cause a minor accident. For everyone else, the small extra cost of higher limits is well worth the peace of mind and asset protection.
How to Prove You Meet New York’s Minimum Insurance Requirement (And Avoid DMV Penalties)
New York requires all drivers to carry proof of valid insurance at all times while operating a vehicle. The state uses an automated electronic system to verify coverage, so fake or expired proof of insurance will be flagged immediately during a traffic stop or registration renewal.
When you purchase a policy from a licensed New York auto insurer, the insurer will file an electronic proof of insurance (eFPI) form with the DMV within 24 hours of your policy start date. You will receive a physical New York proof of insurance card in the mail within 7 to 10 business days. This card must stay in your vehicle at all times, and you must present it to a police officer if asked during a traffic stop.

To verify your own coverage status at any time, you can use the New York DMV’s online insurance verification tool. This tool lets you confirm that your policy is active, meets state minimum requirements, and is properly filed with the DMV. If you are registering a new vehicle or renewing your registration, you will need to provide your policy number to the DMV, which will check your coverage electronically before issuing new plates or a registration sticker.
If your insurance lapses for any reason, your insurer is required to notify the DMV within 24 hours. The DMV will then send you a notice of suspension, and you will have 30 days to provide proof of new coverage before your license and registration are officially suspended. You can avoid this by setting up automatic premium payments with your insurer to prevent accidental lapses.
Common Mistakes That Trigger NY Insurance Fines, Suspensions, and Lapses
Most New York insurance penalties stem from simple, avoidable errors, not intentional fraud. One of the most common mistakes is letting a policy lapse when switching insurers, even for a single day. Your old insurer will report the lapse to the DMV automatically, triggering a $50 per day late fee before you even have a new policy in force.
Another frequent error is forgetting to add a new teen driver to your policy within 30 days of them getting their license. The DMV’s electronic verification system will flag the driver as uninsured immediately, leading to a fine and possible suspension for both the teen and the policyholder.
Using an out-of-state insurance policy that does not meet New York’s 25/50/25 limits is another common trigger. If you move to New York from another state, you only have 30 days to switch to a NY-compliant policy. Drivers who let their registration expire and fail to renew their insurance at the same time often get hit with double penalties, as the DMV will flag both the lapsed registration and lapsed insurance at once.
25/50/25 Minimum vs. Higher Coverage Tiers: What’s Actually Worth It?
The gap between New York’s state minimum and even a mid-tier coverage limit is surprisingly small for most drivers. Let’s break down the most common coverage tiers side by side to see where the value lies.

| Coverage Tier | Per-Person BI | Per-Accident BI | Property Damage | Average Annual Premium (NY, clean record) |
|---|---|---|---|---|
| State Minimum (25/50/25) | $25,000 | $50,000 | $25,000 | ~$1,650 |
| Mid-Tier (50/100/50) | $50,000 | $100,000 | $50,000 | ~$1,780 |
| Standard High (100/300/100) | $100,000 | $300,000 | $100,000 | ~$2,100 |
| High-Net-Worth (250/500/250) | $250,000 | $500,000 | $250,000 | ~$2,650 |
As of 2026, upgrading from the 25/50/25 minimum to a 50/100/50 tier costs an average of $130 extra per year, or roughly $11 per month. That extra $11 covers double the per-person bodily injury limit and double the property damage cap. For drivers with a mortgage, savings, or a vehicle worth more than $5,000, that small premium bump is a no-brainer.
Drivers with no assets and a low-value car may stick with the minimum, but even then, the $11 monthly difference is rarely a financial burden for most households.
2024 New York Minimum Required Insurance: Real Pricing and Claims Data
Numbers make the risk of underinsuring far clearer than generic warnings. Let’s look at the actual pricing and claims data for New York drivers as of 2024 to put the 25/50/25 limits in context.
New York’s average annual premium for minimum required coverage is $1,650 for drivers with a clean record, per New York DFS data. That number jumps to $2,200 for drivers in New York City, where repair and medical costs are roughly 30% higher than the state average. Upstate New York drivers in low-cost rural counties can pay as little as $1,100 per year for the same minimum coverage.
On the claims side, the 2023 average New York bodily injury claim cost was $22,000, per NAIC data. The average property damage claim cost was $4,700. If you cause a multi-car accident with two injured parties, your $50,000 per-accident bodily injury limit could be exhausted in a single afternoon.
You would be on the hook for any remaining medical bills, lost wages, and pain and suffering costs out of your own pocket.
New York Insurance Compliance Rules You Can’t Afford to Ignore
New York’s insurance rules go far beyond the 25/50/25 minimum numbers printed on your policy. Several lesser-known regulations can catch drivers off guard if they don’t know they exist.
New York’s no-fault insurance law requires every policy to include at least $50,000 in personal injury protection (PIP) coverage, separate from the 25/50/25 liability limits. PIP pays for your own medical bills and lost wages after an accident, no matter who is at fault. You cannot reject PIP coverage in New York, and you cannot use your liability limits to pay for your own medical costs.
If you are required to file an SR-22 certificate of financial responsibility, you must carry at least the 25/50/25 minimum limits for three consecutive years to have the SR-22 removed from your record. The SR-22 is a form filed with the DMV by your insurer to prove you carry the required coverage, and it is required for drivers with a DUI, multiple at-fault accidents, or a history of driving without insurance.
Out-of-state drivers who operate a vehicle in New York for more than 30 days must carry coverage that meets or exceeds New York’s 25/50/25 limits. If you are from a state with lower minimums, you need to purchase a non-owner NY policy or upgrade your existing policy to meet the state’s requirements. The DMV can verify out-of-state coverage electronically, so you cannot avoid the requirement by claiming you are just visiting.
All of these rules are enforced by the New York State Department of Financial Services, which oversees all auto insurance policies sold in the state. The DFS regularly audits insurers to make sure they are compliant with state regulations, and it investigates consumer complaints about denied claims or unfair premium hikes.
Quick Decision Guide: Are You Covered Enough Under New York’s 25/50/25 Rules?
Use this simple if-then guide to decide if the 25/50/25 minimum is enough for your situation, or if you need to upgrade your coverage.
If you have no significant assets, no home, less than $10,000 in savings, and no retirement accounts, the 25/50/25 minimum may be enough. This applies if you also drive a vehicle worth less than $5,000, have no teen or new drivers on your policy, do not work for a ride-share or delivery service, and live in an upstate New York county with low average claim costs.
If any of the above are not true, you need higher liability limits. Upgrade to at least a 50/100/50 tier if you have a mortgage, savings, or a vehicle worth more than $5,000. Upgrade to a 100/300/100 tier if you have teen drivers, live in New York City or Long Island, or drive for ride-share or delivery services.
If you have a net worth over $500,000, add a $1 million umbrella insurance policy on top of your auto liability limits to protect your assets from catastrophic accident claims.
If you are unsure what tier to choose, ask your insurer to run quotes for 50/100/50 and 100/300/100 coverage alongside the state minimum. The premium difference is almost always small enough to justify the extra protection.
Frequently Asked Questions
Is New York’s 25/50/25 minimum liability insurance enough?
For most drivers, no. The 25/50/25 minimum only covers a fraction of the costs from a serious accident. The 2023 average New York bodily injury claim cost was $22,000, per NAIC data, and a single severe accident can easily exceed the $25,000 per-person and $50,000 per-accident caps.
Only drivers with no assets and a low-value vehicle should rely on the state minimum alone.
What happens if I drive in New York with out-of-state insurance?
If you operate a vehicle registered in another state in New York for more than 30 days, your policy must meet or exceed New York’s 25/50/25 limits. If your out-of-state policy has lower limits, you must purchase a non-owner New York policy or upgrade your existing coverage within that 30-day window. The DMV can verify out-of-state coverage electronically, so non-compliant policies will be flagged immediately.
How do I prove I have New York’s minimum required insurance?
Your insurer files electronic proof of insurance with the New York DMV within 24 hours of your policy start date. You will receive a physical proof of insurance card to keep in your vehicle within 7 to 10 business days. You can also verify your active coverage at any time using the New York DMV’s online insurance verification tool.
Can I be sued for more than New York’s 25/50/25 liability limits?
Yes, you can. The 25/50/25 limits are the maximum your insurer will pay for an at-fault claim. If a court awards a victim more than those caps, you are personally responsible for the remaining balance.
This can lead to wage garnishment, property liens, or bankruptcy if you do not have the funds to pay the judgment out of pocket.
Does New York’s 25/50/25 minimum cover my own car repairs?
No. The 25/50/25 limits only cover damages you cause to other people and their property. To cover your own vehicle repairs after an accident you cause, you need to add collision coverage to your policy.
If your car is damaged by a non-collision event (theft, vandalism, weather), you need comprehensive coverage. Neither is required by New York law.
When does New York require me to carry more than the 25/50/25 minimum?
You are required to carry higher limits if you have a financed or leased vehicle, as lenders require full coverage including higher liability limits. You will also need higher limits if you are required to file an SR-22 certificate of financial responsibility after a DUI, multiple at-fault accidents, or a history of driving without insurance.