
North Carolina aggressive driving penalties and impact on insurance premiums can hit your wallet harder than you expect. A single conviction often triggers fines, court costs, and a long-term insurance surcharge that can add up to thousands over three years. As of 2026, North Carolina’s Safe Driver Incentive Plan (SDIP) means even a first offense can raise your premium by 25% or more.
The state treats aggressive driving as a serious traffic violation, and insurers respond by reclassifying you as high-risk. Understanding the exact penalties and how they affect your rates helps you make smarter decisions after a citation.
Quick Answer
North Carolina aggressive driving penalties include fines up to $1,000. It adds 5 points to your license. Your insurance premium can rise 25, 50%.
These surcharges last 3 years under the SDIP. Points stay on your record for 3 years.
Why accurate NC aggressive driving penalty and insurance info is non-negotiable
Wrong assumptions about North Carolina’s traffic laws can cost you dearly. If you misjudge whether your behavior qualifies as aggressive driving, you might plead guilty to a charge that carries harsher penalties than you expected. Insurers use the state’s point system to adjust your rates, so even a minor error in understanding the violation can lead to years of overpaying.
The financial impact isn’t just the fine. The Safe Driver Incentive Plan (SDIP) adds surcharges that compound over time, and a single conviction can follow you for three years. Knowing the exact rules helps you avoid unnecessary costs and make informed decisions in court.
Core facts: What counts as aggressive driving (vs reckless driving) under North Carolina law
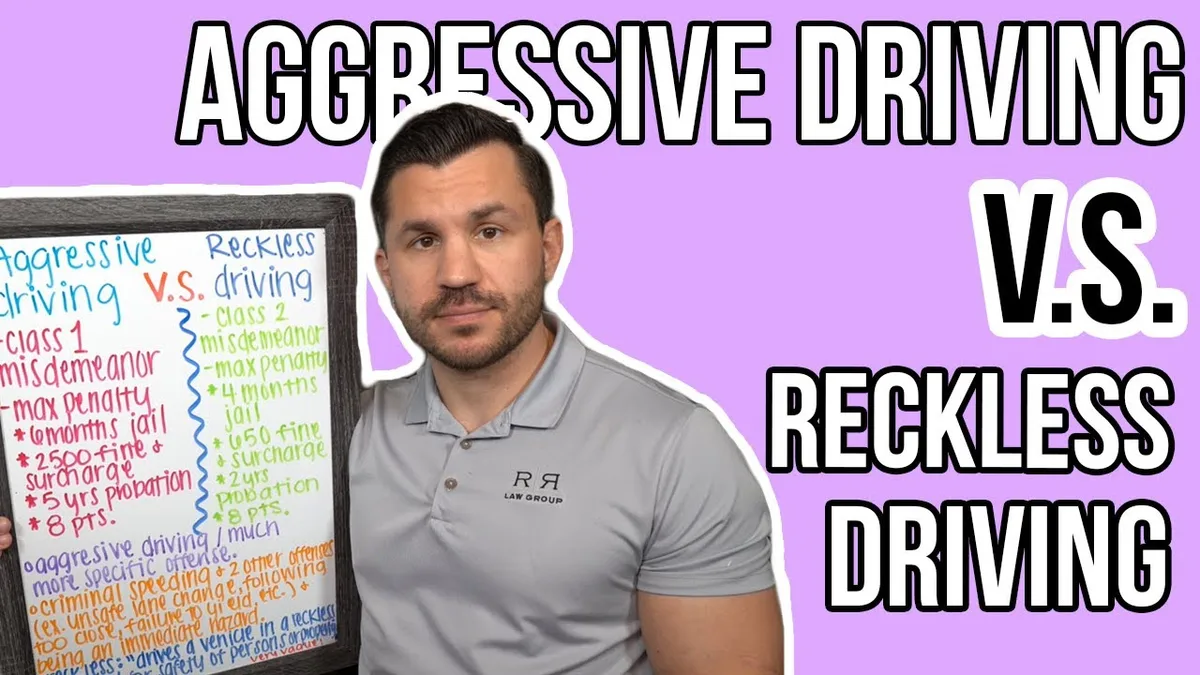
North Carolina defines aggressive driving under NC General Statute § 20-141.3. It involves committing at least two specific violations in a single, continuous act. These include speeding, tailgating, unsafe lane changes, or running red lights.
Reckless driving, under NCGS § 20-140, is a more severe charge. It covers willful or wanton disregard for safety, often involving higher speeds or more dangerous behavior. The key difference is intent and severity.
Aggressive driving is a pattern of violations, while reckless driving is a single, more extreme act.
Common aggressive driving behaviors include:
- Excessive speeding (often 15+ mph over the limit)
- Following too closely (tailgating)
- Erratic or unsafe lane changes
- Running stop signs or red lights
- Failing to yield the right of way
Official penalties for North Carolina aggressive driving, by offense severity
North Carolina treats aggressive driving as a Class 2 misdemeanor. First-time offenders face fines up to $1,000, but the actual amount varies by county and judge. You’ll also receive 5 points on your license, which triggers the SDIP surcharge.
Repeat offenses escalate quickly. A second conviction within three years can lead to higher fines and a license suspension of up to 90 days. Aggravated cases, such as those involving accidents or injuries, may result in jail time.
Here’s a breakdown of penalties by offense severity:
| Offense Type | Fine Range | License Points | License Suspension | Jail Time |
|---|---|---|---|---|
| First-time aggressive driving | Up to $1,000 | 5 | None (unless ordered) | Up to 30 days |
| Repeat offense (within 3 years) | Up to $1,000 | 5 | Up to 90 days | Up to 60 days |
| Aggravated (accident/injury) | Up to $1,000+ | 5+ | Up to 1 year | Up to 1 year |
Court costs add another $200, $400 to your total expense. These fees are separate from the fine and must be paid regardless of the verdict.
Key risk: How NC DMV points and the Safe Driver Incentive Plan (SDIP) amplify long-term costs
North Carolina’s DMV point system directly impacts your insurance premiums. Each point on your license increases your risk classification, and insurers use this to justify higher rates. The Safe Driver Incentive Plan (SDIP) adds surcharges based on the number of points you accumulate.
Here’s how the SDIP works as of 2026:
| Points on License | SDIP Surcharge | Duration |
|---|---|---|
| 1 | 25% | 3 years |
| 2 | 45% | 3 years |
| 3 | 65% | 3 years |
| 4+ | 90% | 3 years |
Aggressive driving adds 5 points to your license, which means you’ll face the maximum 90% surcharge for three years. This surcharge is applied on top of your base premium, so the financial impact compounds over time. For example, if your annual premium is $1,200, a 90% surcharge adds $1,080 per year, totaling $3,240 over three years.
Exact insurance premium impact of aggressive driving violations in North Carolina
Insurance companies in North Carolina treat aggressive driving convictions as high-risk behavior. The exact premium increase depends on your insurer, but most drivers see a 25, 50% hike after a single conviction. Some insurers may even non-renew your policy if you have multiple violations.
Here’s a general breakdown of average premium increases by violation type:
| Violation Type | Average Premium Increase | Duration of Impact |
|---|---|---|
| Aggressive driving (first offense) | 30–40% | 3 years |
| Reckless driving | 40–60% | 3–5 years |
| Speeding (15+ mph over limit) | 20–30% | 3 years |
| Tailgating | 15–25% | 3 years |
Young drivers and those with prior violations typically face the steepest increases. If you’re already classified as high-risk, an aggressive driving conviction could push your premiums into unaffordable territory. Shopping around for new insurance after a conviction is often necessary, but be prepared for higher quotes across the board.
Safe practices to minimize penalty and insurance damage after a citation
Act fast to reduce the damage from a citation. Ignoring the ticket leads to automatic license suspension and extra late fees.
Review the citation for errors, like wrong dates or vehicle details, before you respond. Many North Carolina counties let you reduce points or fines by completing an approved defensive driving course before your court date. Check with your local traffic court to confirm eligibility, as rules vary by county.
Common costly mistakes to avoid with NC aggressive driving tickets
Ignoring the citation is the most expensive common error. A missed deadline adds late fees, triggers license suspension, and can lead to an arrest warrant.
Pleading guilty without checking your options often means missing out on reduced charges or traffic school that limits points. Failing to tell your insurer about a conviction leads to a retroactive premium hike when they find the violation on your record. Commercial drivers frequently overlook that aggressive driving convictions can disqualify them from operating commercial vehicles, leading to lost income.
Step-by-step actions to take after receiving an aggressive driving citation in NC
Your citation lists a response deadline, usually 30 days from the issue date. First, check the ticket for accuracy and note your court date and fine amount.
Next, choose to pay the fine, which counts as a guilty plea, or contest the charge in court. If you contest, gather evidence like dashcam footage or witness statements before your hearing. After the court rules, notify your insurer within 10 days to avoid coverage issues.
Confirm the violation was recorded correctly on your DMV point record.
When to seek legal or insurance support for NC aggressive driving charges
Hire a traffic attorney if you have prior license points, face a suspension, or had an accident with the citation. An attorney can negotiate a reduced charge with fewer points and lower surcharges.
Commercial drivers should almost always hire a lawyer, as a conviction can end their career. Contact your insurance agent as soon as you get the citation, not just after a conviction, to ask about accident forgiveness or high-risk policy options. Some insurers offer first-time violation forgiveness for drivers with clean prior records.
Real scenario: 3-year total cost of a single NC aggressive driving conviction
A 32-year-old driver in Raleigh, NC, got an aggressive driving citation for speeding 18 mph over the limit plus tailgating. The court imposed a $900 fine, $300 in court costs, and 5 license points.
Their annual premium was $1,350 before the conviction. The 5 points triggered the maximum 90% SDIP surcharge, adding $1,215 per year for three years. The total 3-year cost hit $6,180, including fines, court costs, and surcharges.
This driver’s credit score also dropped 15 points after the unpaid fine went to collections for a missed deadline.
Verified summary: NC aggressive driving penalties and insurance key facts
Aggressive driving in North Carolina is a Class 2 misdemeanor under NC General Statute § 20-141.3. A first conviction carries a fine up to $1,000, plus 5 license points and court fees between $200 and $400.
The 5 points trigger the maximum 90% SDIP surcharge for three years, adding an average of $1,000 to $1,500 per year to your insurance premium. Repeat convictions within three years lead to license suspension of up to 90 days, higher fines, and potential jail time.
Points stay on your license for three years, and the surcharge applies to all auto insurance policies in the state, even if you switch carriers. A single aggressive driving conviction can cost $6,000 or more over three years when you combine fines, court costs, and insurance surcharges.
FAQs: NC Aggressive Driving Penalties and Insurance Premiums
How long do aggressive driving points stay on your license in North Carolina?
Aggressive driving adds 5 points to your license, and these points stay on your record for three years from the conviction date. The Safe Driver Incentive Plan (SDIP) surcharge also lasts three years, even if you earn no additional points during that time. Points drop off automatically after three years if you have no new violations.
Does aggressive driving increase car insurance more than a speeding ticket in NC?
Yes, aggressive driving typically raises premiums 30 to 40% on average, while a standard speeding ticket (15+ mph over the limit) increases rates 20 to 30%. Aggressive driving adds 5 points, while most speeding tickets add 2 to 3 points, leading to a higher SDIP surcharge and larger premium hike. Drivers with prior violations or young drivers under 25 often see even steeper increases.
Can you get an aggressive driving ticket dismissed in North Carolina?
You may get a ticket dismissed if the citing officer cannot appear in court, or if your attorney finds procedural errors on the citation. You can also reduce the charge to a lesser violation with fewer points by completing a pre-trial diversion program or defensive driving course, depending on your county’s rules. Check with your local traffic court to confirm eligibility for these options before your court date.
What is the difference between aggressive driving and reckless driving in NC?
Aggressive driving requires at least two traffic violations committed in a single continuous act, like speeding plus tailgating. Reckless driving is a single act of willful or wanton disregard for safety, like excessive speeding in a school zone, and carries harsher penalties including longer license suspensions and higher fines. Both charges add points to your license and trigger SDIP surcharges, but reckless driving is a more serious offense with longer-lasting consequences.
Do you have to tell your insurance company about an aggressive driving ticket in NC?
Yes, North Carolina law requires insurers to check DMV records annually, so they will find the violation even if you do not report it. Failing to disclose a conviction can lead to policy cancellation or denial of a claim, and you will still face the premium surcharge when the insurer discovers the violation. Notify your insurer as soon as possible after receiving a citation to avoid coverage issues.